You got the deal under contract. Nice work! Now comes the part nobody posts about: actually getting it to the closing table.
For investors, a delay is rarely just an inconvenience. You might have private money lined up, contractors on the calendar, a tenant-buyer waiting to move in, or another deal counting on this one’s proceeds. One missing signature or surprise lien can knock the whole thing sideways.
The good news? Most closing delays are preventable if you know where to look, and you look early. Here are the 10 most common culprits and how to stop each one in its tracks.
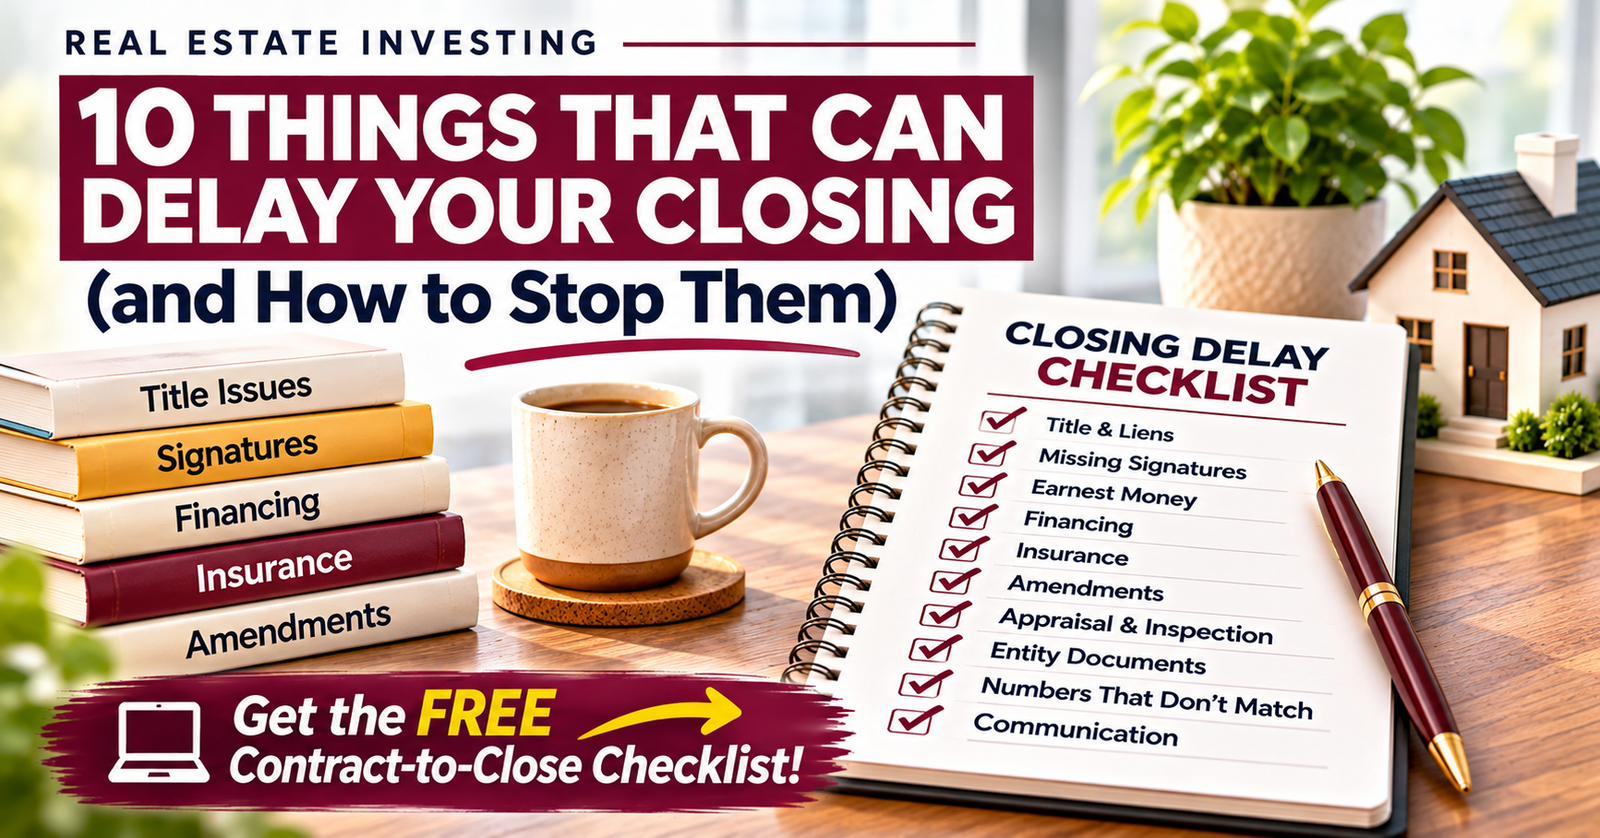
Free download: Want every step from signed contract to closing day in one printable list? Grab the Contract-to-Close Checklist.
1. Unresolved Title Issues
Title problems top the list for a reason. The search can turn up liens, unpaid taxes, judgments, or a mortgage the seller swears was paid off years ago, except the release was never recorded. Until that’s cleared, the title company can’t insure the property, and you’re not closing.
Stay ahead of it: Open title the day the contract is signed, request the preliminary commitment, and review the exceptions right away. Don’t wait until closing week to find out whether your seller can actually deliver clean title.
2. Missing Signatures
A deal can be fully funded and legally sound and still stall over one blank initial line. Think an amendment nobody signed, a spouse or co-owner who was left out, or an LLC rep with no proof of authority.
Stay ahead of it: Confirm every party’s legal name and who can sign for any entity. Then check every page for signatures, initials, and dates before you call it done.
3. Earnest Money Hiccups
Buyers send funds to the wrong place, wire instructions show up late, or someone waits until the last possible day. Depending on your contract, a missed EMD deadline can put the buyer in default.
Stay ahead of it: Confirm the amount, deadline, and escrow holder right after signing. Send funds early and keep written confirmation of receipt. And always verify wiring instructions by calling the title company at a number you know is real. Wire fraud is no joke.
4. Financing Delays
A preapproval letter isn’t a loan. Missing income docs, credit changes, appraisal issues, or unmet underwriting conditions can all stall funding. Private, hard money, and DSCR lenders can hold things up too, waiting on entity docs or insurance.
Stay ahead of it: Ask the lender for the list of outstanding conditions, send documents fast, and confirm the clear-to-close and funding dates. Don’t take “we’re good” on faith. Verify.
5. Insurance Problems
Insurance often gets treated as a last-minute checkbox. That’s risky with vacant, distressed, older, or manufactured homes, or anything you plan to rehab. Some properties won’t qualify for a standard policy at all.
Stay ahead of it: Call your agent as soon as you’re under contract and be upfront about the property’s condition and use. Confirm the lender’s requirements and get the binder before closing. On creative finance deals, make sure the policy fits the real ownership and financing structure.
6. Amendments That Never Got Signed
Everyone agrees on the phone to push closing back a week, but nobody signs the amendment. Title keeps working toward the old date, and suddenly no one knows which deadline is real.
Stay ahead of it: Put every change in writing, get all the signatures, and send the executed amendment to title, the lender, and the agents. Then update your timeline. A text message is not an amendment.
7. Appraisal and Inspection Surprises
A low appraisal can force a renegotiation or require the buyer to bring more cash. An inspection can uncover roof, plumbing, electrical, or structural problems. And sometimes inspectors and appraisers are simply booked out.
Stay ahead of it: Schedule inspections and order the appraisal as early as the contract allows. Make sure the property is accessible, review reports quickly, and wrap up negotiations before deadlines pass.
8. Entity Documentation Gaps
Buying through an LLC or trust? Title may want your articles of organization, operating agreement, certificate of good standing, EIN, and a signing resolution. Trouble starts when the name on the contract doesn’t match state records or the signer can’t prove authority.
Stay ahead of it: Confirm the exact entity name before the contract is written, and send documents early. Your contract, title commitment, closing docs, and funding should all show the same entity.
9. Numbers That Don’t Match
Buyer, seller, lender, and title can each have different figures for credits, prorations, payoffs, or fees. A seller expecting a certain payout may discover an unpaid tax bill changes the math. Creative deals with multiple funding sources, seller financing, or assignments add even more moving parts.
Stay ahead of it: Review the settlement statement early. Verify the price, deposits, payoffs, prorations, and assignment fees, and resolve every discrepancy before signing day.
10. Communication Gaps
Sometimes the biggest delay is just people not talking. The buyer assumes title has everything. Title is waiting on the lender. The lender needs an updated insurance binder. And nobody notices the closing date is in trouble until it’s too late.
Stay ahead of it: Name one point of contact, send regular updates, chase down unanswered emails, and confirm everything is ready several days out. This is exactly where a transaction coordinator earns their keep.
Your Best Defense: A Transaction Checklist
Most delays aren’t anyone’s fault. A dozen small tasks get spread across different people, and no one sees the whole picture. A simple checklist fixes that. At a minimum, track:
- Contract fully executed and distributed
- Earnest money deposited and confirmed
- Title opened and commitment received
- Inspections and appraisal completed
- Financing and underwriting on track
- Insurance confirmed
- Amendments fully signed
- Entity documents submitted
- Payoffs and closing figures verified
- Closing date, time, and location confirmed
Want the full version? The free Contract-to-Close Checklist breaks these milestones into 35+ steps across every phase of your deal, plus a contacts sheet and the red flags to fix right away.
Start preparing for closing the moment the contract is signed, not the week before.
Final Thoughts
Great investing isn’t just about finding deals and negotiating terms. It’s about having a reliable process for getting those deals across the finish line.
Whether you’re buying a rental, wholesaling, using private money, offering seller financing, or closing a contract for deed, one rule holds: the earlier you spot a problem, the easier it is to fix.
Stay organized, communicate often, and follow up relentlessly. You’ll protect your timeline and build a reputation as the investor who gets deals done.
At Turnkey TC Solutions, that’s our job. We keep your transactions organized and moving from contract to close, so you can focus on finding and funding your next deal.
Ready to keep your next deal on schedule? Download the free Contract-to-Close Checklist and start using it the day your contract is signed.
Leave a Reply