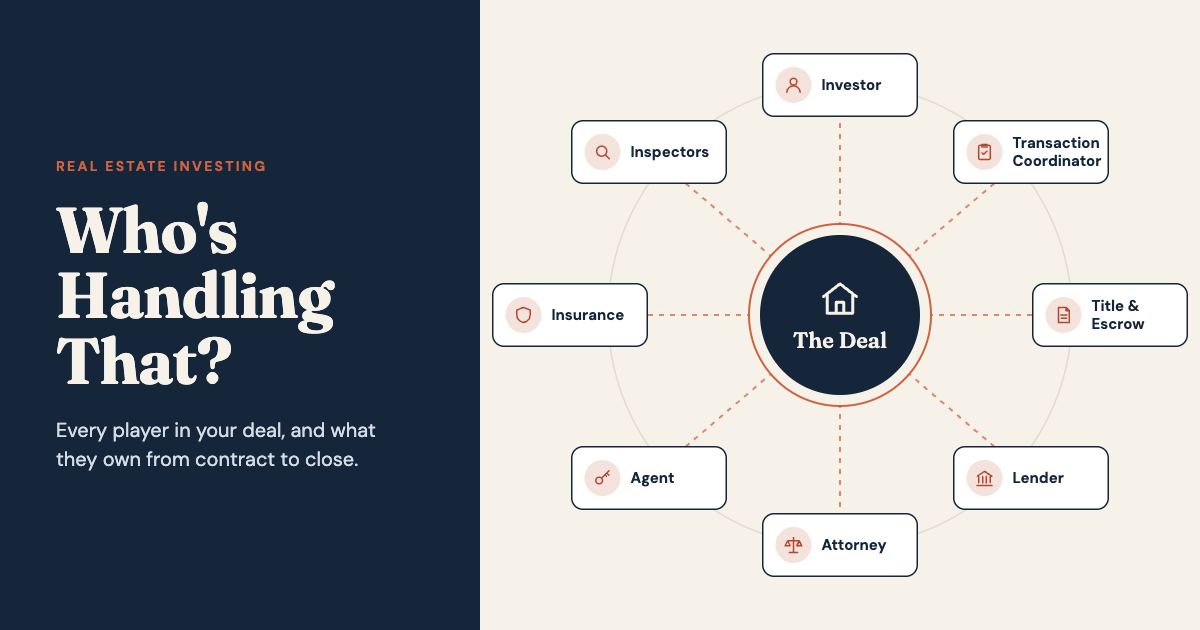
Real estate deals have a lot of moving parts.
Even a simple cash purchase can involve a buyer, seller, agents, a title company, an attorney, a lender, an insurance agent, inspectors, and a transaction coordinator. Add seller financing, private money, subject-to, or another creative structure, and the cast of characters grows fast.
Here’s where things go wrong: everyone assumes someone else is handling it.
The title company thinks the buyer is getting the insurance info. The buyer thinks the TC ordered the inspection. The lender is waiting on the title commitment. And the seller still hasn’t signed the amendment.
Meanwhile, the closing date isn’t moving.
When you know exactly who owns each piece of the deal, you avoid missed deadlines, pointless delays, and that familiar last-minute scramble. Here’s a practical breakdown of who does what.
The Investor (That’s You)
The buck stops with you.
You can hire professionals to handle specific pieces, but you’re still the one making the business decisions. As the buyer, you’ll typically need to:
- Sign contracts and amendments promptly
- Deposit earnest money on time
- Decide whether to move forward after inspections or due diligence
- Secure financing
- Provide entity documents if you’re buying through an LLC
- Get insurance in place
- Approve the closing figures
- Bring funds to closing
- Make the call when title, financing, inspection, or seller issues come up
Your transaction coordinator can keep you informed and keep tasks moving, but they generally can’t make financial or legal decisions on your behalf.
Your move: The moment a contract is signed, make sure someone lists every key deadline in the agreement. At minimum, track:
- Earnest money deadline
- Inspection or due diligence deadline
- Financing deadline
- Title objection deadline
- Insurance deadline
- Closing date
Don’t trust your memory. Write it down.
The Transaction Coordinator
Think of your TC as the hub of the deal. Their job is to get you from signed contract to closed deal by managing communication, documents, deadlines, and follow-up.
Depending on what’s included in their service, a TC may:
- Pull the key dates from the executed contract
- Build a transaction timeline
- Open the file with title or escrow
- Send contracts and amendments to the right people
- Track earnest money
- Follow up on title work
- Coordinate with the lender
- Request insurance information
- Track inspections
- Chase down missing signatures
- Handle closing logistics
- Keep you updated
- Organize the final transaction file
A good TC does more than drop documents into a folder. Their real value is spotting what still needs to happen and following up until it does.
If title says they’re waiting on LLC documents, your TC flags it for you and gets those documents delivered. If the lender needs the title commitment, your TC chases title and makes sure it lands in the lender’s inbox.
Your move: Ask your TC exactly what their service includes. Not every TC offers the same thing, so don’t assume.
The Title or Escrow Company
In most closings, title does a lot of the heavy lifting. Depending on your state and the deal, they may:
- Run the title search
- Issue the title commitment
- Flag liens or ownership issues
- Hold earnest money
- Prepare settlement statements
- Coordinate the signing
- Handle incoming and outgoing funds
- Record the deed and other documents
- Issue title insurance
One thing they won’t do is magically fix every title problem. If a judgment, unreleased mortgage, probate issue, tax deed, or ownership discrepancy turns up, you may need extra documentation or legal help to clear it.
Your move: Don’t wait until closing week to check in on title. Once the file is open, ask regularly:
- Is the title search done?
- Are there any title requirements?
- Do you need anything from the buyer or seller?
- Is anything likely to delay closing?
The Real Estate Agent
When agents are involved, they usually handle negotiating and papering the deal. An agent may:
- Prepare or submit offers
- Negotiate price and terms
- Communicate with the other side’s agent
- Coordinate inspections
- Draft amendments or extensions
- Answer contract questions within the scope of their license
Agents and TCs often work hand in hand, but their jobs are different. The agent focuses on representation, negotiation, and the contract. The TC focuses on execution, organization, deadlines, and communication once the contract is signed.
Your move: Decide early who’s responsible for drafting amendments. The last thing you want is to discover two days before closing that everyone assumed someone else was writing the extension.
The Lender
If there’s financing, the lender controls a big chunk of your timeline. They may require:
- The purchase contract
- The title commitment
- An appraisal
- Proof of insurance
- Entity documents
- Your financial documents
- Property information
- Closing protection documents
- Final settlement figures
Private and hard money loans may also call for promissory notes, mortgages, deeds of trust, personal guarantees, or other loan documents.
Here’s the catch: your deal can be completely clear on the title side and still fail to close because the financing isn’t ready.
Your move: Ask your lender early, “What do you need from us, from title, and on the property to clear this loan for closing?” Then track every item on that list.
The Attorney
Attorneys become essential when a deal involves unusual legal issues or creative financing. You may need one for:
- Seller-financing documents
- Promissory notes
- Mortgages or deeds of trust
- Contracts for deed
- Lease-option agreements
- Entity questions
- Probate situations
- Tax deed issues
- Title disputes
- Complex amendments
- State-specific legal requirements
Your TC can gather information and coordinate document delivery, but a TC is not a substitute for legal counsel.
Your move: If your deal needs custom legal documents, call the attorney early. Asking for seller-financing docs three days before closing is a reliable way to push your closing date.
The Insurance Agent
Insurance is one of the most common last-minute scrambles. Depending on the deal, your agent may need:
- The property address
- Purchase price
- Loan amount
- Lender name
- Mortgagee clause
- Property condition
- Occupancy status
- Entity ownership details
If you’re financing, your lender will likely want proof of coverage before releasing funds.
Your move: Start the insurance conversation as soon as you know you’re moving forward. Not closing week.
Inspectors and Other Vendors
Depending on the property, you might also bring in home inspectors, roofers, electricians, plumbers, surveyors, appraisers, or contractors.
What they find can decide whether you move forward, walk away, or renegotiate. Your TC may schedule appointments or track deadlines, but reviewing the results and making the investment call is on you.
The Golden Rule: Every Task Needs an Owner
Most closing headaches aren’t caused by complicated legal problems. They happen because nobody clearly owns the task.
Instead of saying, “We need the insurance,” say:
“Cindy will call the insurance agent today and send the binder to the lender and title by Thursday.”
Instead of saying, “We’re waiting on title,” say:
“The TC will follow up with title on Tuesday for the commitment and any outstanding requirements.”
Every important task should have four things:
- An owner
- A deadline
- A status
- A follow-up date
That one simple habit clears up a surprising amount of transaction chaos.
Build One Central Checklist
For every deal, keep one place where you can see the whole picture at a glance:
Contract
- Executed contract received
- Key dates entered
- Amendments completed
Earnest Money
- Amount confirmed
- Deposit instructions received
- Deposit completed
Title
- File opened
- Title search completed
- Commitment received
- Requirements reviewed
- Issues resolved
Financing
- Lender documents submitted
- Appraisal completed
- Insurance provided
- Loan cleared to close
Closing
- Final settlement statement reviewed
- Closing funds confirmed
- Signing scheduled
- Documents recorded
Post-Closing
- Final documents received
- Recorded deed received
- Title policy received
- Transaction file completed
Stop Running Your Closings From Your Inbox
Email is for communication. It’s not a transaction management system.
Once you’re juggling several properties, it gets easy to lose the thread. One deal is waiting on title. Another needs an amendment. Another is stuck on insurance. Another needs the lender to sign off on final figures.
That’s exactly where transaction coordination earns its keep.
Instead of waking up every day wondering, “What am I forgetting?”, you should be able to glance at your pipeline and instantly see what’s done, what’s outstanding, who owns it, and what needs a nudge.
When everyone knows their role, and someone is actively keeping all the pieces moving, deals get a whole lot easier to manage.
And for investors trying to grow, that means less time chasing paperwork and more time finding the next deal.
Leave a Reply